Casablanca Achieves 'Investment Grade' Rating from S&P Global Ratings
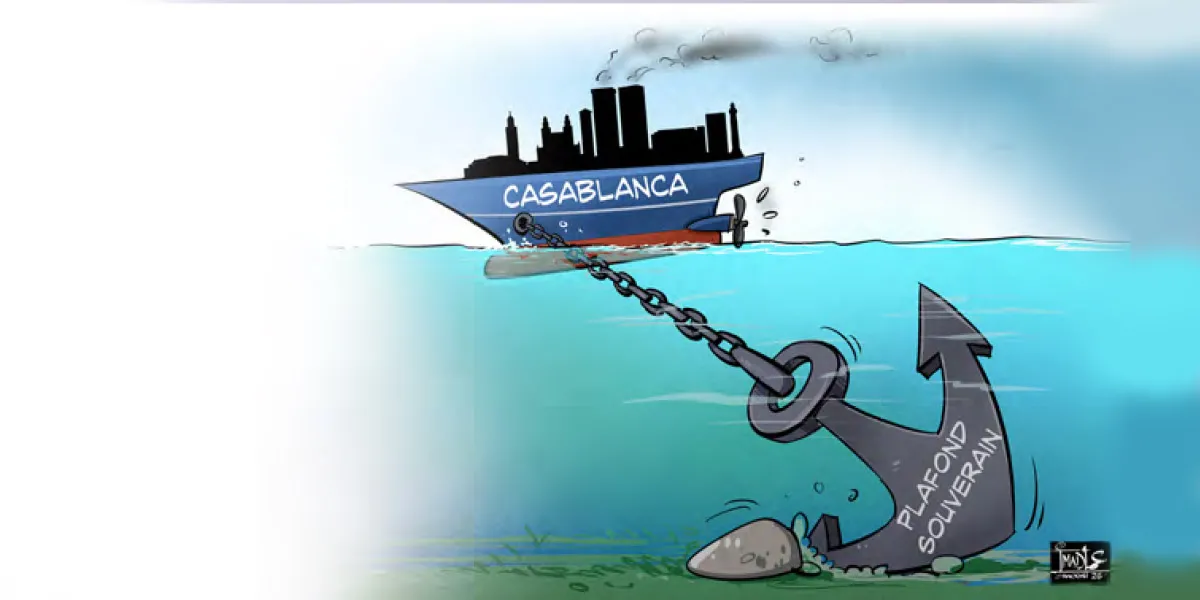
In a significant development for Morocco's economic landscape, S&P Global Ratings has awarded Casablanca a long-term rating of 'BBB-' and a short-term rating of 'A-3' with a stable outlook. This rating positions the city within the 'Investment Grade' category, indicating the quality of credit is sufficient for investment purposes. Notably, S&P has assessed Casablanca's intrinsic credit profile at 'bbb+', which is two notches higher than the sovereign rating of Morocco. This distinction underscores the city's robust economic fundamentals and improving fiscal performance, despite highlighting the institutional constraints that warrant caution.
According to S&P, the rationale behind the 'BBB-' rating resides in the limitations of Morocco's institutional framework. The agency emphasizes that local authorities in Morocco may struggle to maintain a credit quality superior to that of the state, especially in the face of financial pressures. This is largely attributed to their structural dependence on public transfers and shared fiscal revenues, which restrict their financial autonomy.
Economic Strength and Fiscal Outlook
Casablanca's economic weight is considerable, contributing approximately 20% to Morocco's GDP, making it the principal economic and financial hub of the kingdom. The city hosts a significant concentration of corporate headquarters, financial institutions, and foreign investments, benefiting from a diversified productive base that spans manufacturing, financial services, trade, logistics, telecommunications, and business services. This economic diversification is crucial in mitigating risks associated with sector-specific downturns. S&P also notes the relatively high wealth levels in the Casablanca-Settat region, with an estimated GDP per capita of around $6,800 in 2024, compared to the national average of $4,400. This concentration of economic activity bolsters the municipality's fiscal capacity, with tax revenues projected to increase by approximately 38% from 2019 to 2025 due to improved tax administration, digitalization, and broader tax bases.
However, S&P warns that Casablanca's economic growth does not shield it from structural constraints. Urban growth continues to strain infrastructure, transportation, housing, and public services, while challenges such as unemployment, the prevalence of the informal economy, and climate risks—particularly water stress and urban flooding—persist.
The budgetary outlook appears promising, with S&P projecting continued improvement in operating budget performance. It anticipates an operational surplus rising from 918 million dirhams in 2025 to 1.375 billion dirhams by 2028, with operating revenues expected to reach 5.55 billion dirhams in 2028. This growth will primarily stem from enhanced local tax collection and better management of public space usage.
While S&P predicts moderate expenditure growth as municipal services expand, it highlights that any increase in operational surpluses must align with budgetary control objectives. The agency foresees investment expenditures of 1.84 billion dirhams in 2026, 1.57 billion in 2027, and 2.01 billion in 2028, with a significant portion dedicated to contributions to local development companies.
Furthermore, S&P's analysis suggests a gradual decline in the city's debt, estimating a drop from 3.18 billion dirhams at the end of 2025 to 2.57 billion dirhams by 2028, with debt constituting a moderate percentage of operating revenues. The agency does not foresee significant new borrowing, except for planned draws from existing financing with the World Bank. The liquidity position of Casablanca is viewed positively, with available cash expected to cover more than 100% of debt service over the next year.
Despite these positive indicators, S&P also highlights significant off-balance sheet risks, notably from potential legal liabilities linked to expropriations and public-private partnership obligations. These risks represent commitments that could materialize in the future, emphasizing the need for transparency regarding contractual obligations and the risks associated with the municipal ecosystem.
The report ultimately raises a broader question regarding the financial autonomy of local authorities in Morocco, characterizing the institutional framework as still evolving and imbalanced. The dependence on state transfers and shared tax revenues, along with central government control over local tax collections, limits the financial independence of municipalities. This dependency is the primary reason for the ceiling on Casablanca's rating at the sovereign level, despite its superior intrinsic credit profile.
As reported by leseco.ma.